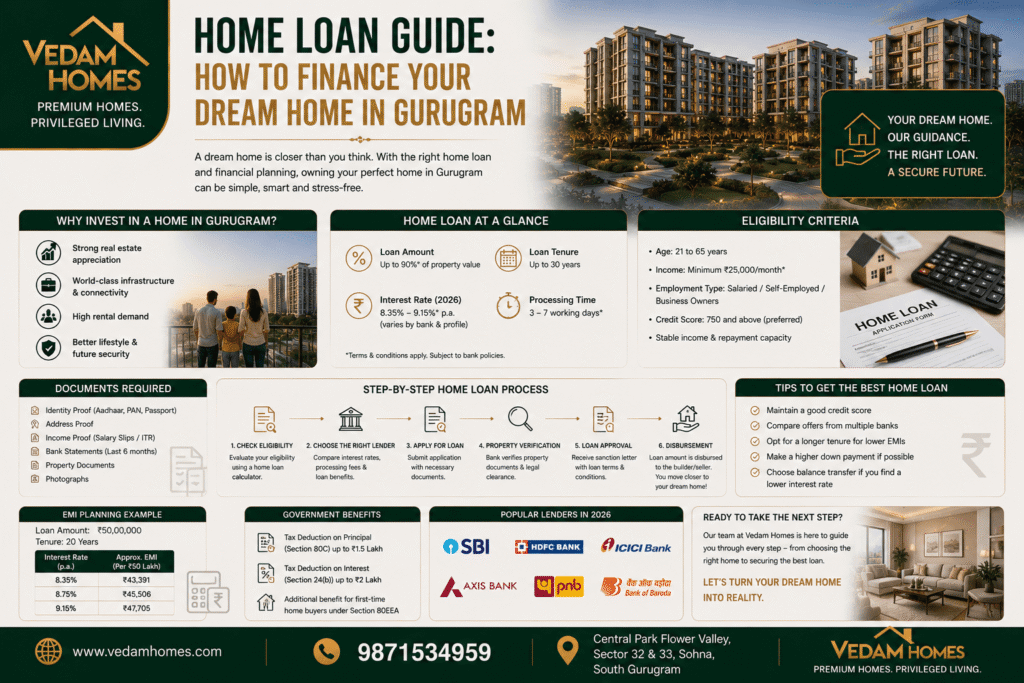
Buying a home is a big financial decision, and more so when you are buying in Gurugram. Gurugram property continues to attract end-users as well as investors owing to the city’s growing corporate ecosystem, expanding infrastructure, premium residential developments, and strong employment base. For most buyers, however, buying a home is about more than just choosing the right location or project. Often the most important question is: How should the purchase be financed?
For many buyers, a home loan is the most realistic way to buy property without having to lay out all their savings at once. However, a home loan is a long-term financial commitment. Interest rate, loan tenure, down payment, processing charges, eligibility, credit profile, property documentation are some of the factors that influence the actual cost of owning a home.
For home buyers looking to buy a house in 2026, India’s lending environment remains a key factor. The Reserve Bank of India (RBI) has maintained status quo on the policy repo rate at 5.25 per cent for now, as the central bank holds a cautious view on inflation and economic conditions. This results in a relatively stable policy-rate environment, but individual home-loan rates still vary by lender, borrower profile, loan amount, and other factors.
For a buyer in Gurugram, the goal should not be to just take the maximum possible loan. The smarter goal is to get a loan that is comfortable for the term of the loan but leaves room for emergencies, lifestyle expenses, and future goals.
What Is a Home Loan?
A home loan is a secured loan by a bank, housing finance company, or other eligible lender to enable an individual to buy, construct, renovate, or in some cases extend a residential property. Usually, the property is used as a collateral for the loan. The borrower repays the amount in the form of principal and interest in the form of EMI (Equated Monthly Instalments).
Say, you are buying a property in Gurugram for Rs 1.50 crore and giving a down payment of Rs 40 lakh. The balance amount of ₹1.10 crore can be arranged through a home loan subject to your eligibility and the lender’s assessment of your income, credit score, and property. The price of the property does not solely determine the exact loan amount. The borrower’s: Lenders also consider:
- Work and earnings
- Existing liabilities
- Credit history and credit score
- Age
- Ability to repay
- Property papers.
- Assessment of property
- Loan to value requirements
- Total financial profile
Why Home Loans Are Important for Gurugram Buyers
Buying property in established and emerging corridors of Gurugram can be a capital intensive affair. Hence, for many households, it may not be possible to pay the full purchase price out of savings. Benefits of a home loan:
1. Keep Your Savings:
Instead of draining your savings account to get into a property, you’ll have the chance to put some of it towards your down payment and still have some cash on hand for emergencies and other financial objectives.
2. Homeownership via regular payments
An EMI is a method to convert a large financial liability into a systematic monthly payment.
3. Tax Advantages
Depending on the prevailing tax laws, type of property, purpose of the loan and tax regime, borrowers could avail of deductions on home-loan interest and/or principal repayment. Buyers are advised to consult with a qualified tax professional to confirm eligibility before making any decisions based on tax benefits.
4. Possible wealth creation
If the property appreciates over the long term, the buyer can profit from the capital appreciation and gradually build ownership equity by paying off the loan. But never assume or expect property to increase in value. “The focus of assessing a home loan should be affordability, not speculation.
How Much Home Loan Can You Afford?
This is one of the most important questions a buyer should answer before buying a property. The fact that lenders are willing to offer you a certain loan amount doesn’t mean you should go for the maximum loan available. A practical approach is to evaluate:
Existing EMIs – Essential Expenses – Emergency Savings – Monthly Income = Affordable EMI Capacity
For example, if a household is earning Rs 3 lakh a month and already has major liabilities, then taking a very large housing loan can create unwanted financial stress. Calculate prior to setting up the property budget:
- First payment
- MIE
- Interest expense
- Upkeep
- Property taxes
- Insurance
- Stamp duty and registration fees
- Cost of interiors and furniture
- Emergency reserves
The net emergency reserve cost of buying a home is higher than the advertized price of the property.
Down Payment: How Much Should You Pay?
In most cases, the home buyer has to provide some of the cost of the property himself/herself and the lender lends the remainder of the eligible amount. A larger down payment can reduce the loan amount and thus the total interest payable.
For instance:
- Property Value: ₹1.5 crore
- Down Payment: 50 Lakh
- Loan Requirement: ₹1 crore (possible)
vs.
- Down Payment: ₹ 30 Lakhs
- Possible Loan Requirement: ₹1.20 crore
The second option gives you more leverage but also increases your EMI and total interest outgo. The right down payment is thus a balance between reducing debt and keeping enough liquidity. Don’t just dump all your savings into property to get the loan down. It’s also vital to have an emergency fund.
Understanding Home Loan Interest Rates in 2026
Interest rate is one of the key components of a home loan as even a small difference can have a big impact on the total amount paid for a long tenure. The RBI’s policy repo rate now stands at 5.25 per cent. In August 2026, the RBI kept the repo rate unchanged at 5.25% to balance between inflation and global economic uncertainties.
But homebuyers shouldn’t assume that a 5.25% repo rate translates into 5.25% home loans. Several factors influence home loan pricing, including:
- Benchmark & Spread Lender
- The credit history of the borrower
- Income
- Amount of loan
- Length of the loan
- Employment profile
- Type of property
- Relationship with the lender
- Market conditions
Floating vs Fixed Interest Rate
Floating rate loans vary with time depending on the prevailing benchmark and the lender’s terms. That makes them cheaper when you have low lending rates, but more expensive if rates go up.
For fixed-rate loans, there is greater certainty of payment for the fixed period or structure applicable. Prices and terms can vary widely from lender to lender. Buyers need to know how and how often interest rates can change on a long term loan.
How EMI Works
Your EMI is mainly based on: Loan Amount + Interest Rate + Tenure
The longer you take to repay, the lower your monthly EMI amount will be, but you will end up paying more interest in total. Higher EMI but lesser tenure can drastically reduce your total interest burden.
For example, a ₹1 crore loan may look manageable over 20 or 25 years because of a lower monthly payment, but the cumulative interest can become very large over such a long period.
Therefore, the goal should not be to achieve the lowest possible EMI. It should be to achieve the most sustainable repayment structure.
Home Loan Eligibility in Gurugram
While eligibility depends on the lender, many institutions consider some common factors.
- Income: If you have a regular income from a business or corporation, it is easier to repay your home laon.
- Credit history: Generally, a good payment history enhances the borrower’s credit profile and may result in better terms.
- Existing loans: Car loans, personal loans, credit card dues, other EMIs impact on availability of repayment capacity.
- Job Stability: The documentation and assessment criteria may vary for salaried and self-employed applicants.
- Age: The lender considers the age of the applicant at the time of borrowing and the age expected at maturity of the loan.
- Property: The lender will also check the property, its paperwork, valuation, and legal position. “It is advisable to get an in-principle or eligibility assessment from a lender before deciding on a property wherever possible. This helps to make a realistic budget.”
Documents Usually Required
Each lender has its own requirements, but home-loan applications generally require such documents as:
- Identity Proof & PAN Card
- Proof of address
- Passport size photographs
- Salary slips for salaried applicants
- Statements from the bank
- Income-tax returns or Form 16
- Employment/business records
- Current loan statements
- Property papers
- Allotment papers or agreement papers
- Approved building/layout plans, where applicable.
Self-employed applicants may be asked for additional financial statements, business documents and income-tax records. For a Gurugram property, property-document verification is very important, as the process of approval of the loan is not a replacement of the buyer’s own legal due diligence.
Home Loan Process: Step-by-Step
Step 1. Track Your Credit Profile
Before applying, do check your credit history and existing liabilities.
Step 2: Define Your Budget
Know your down payment, affordable EMI, and total purchase budget.
Step 3: Find Lenders
Don’t just look at the advertized interest rates to compare lenders; Contrast:
- Rate of interest
- benchmarking
- Processing fee.
- Legal/technical fees
- Insurance requirements
- Prepayment conditions
- conversion fees
- Documentation fees
- Customer service
Step 4: Approve Your Loan
Provide necessary financial and personal documents.
Step 5: Property Confirmation
The final disbursement is usually preceded by legal and technical checks from the lender.
Step 6: Paperwork
To get a loan, you need to complete the formalities of your loan agreement, property papers, etc.
Step 7. Disbursement of Loan
The lender disburses funds according to applicable terms and disbursement schedule.
Special Considerations for Under-Construction Properties
If you are buying a property that is under construction in Gurugram, then the disbursal of loans may be in stages as per the progress of construction and as per the terms of the lender. Buyers must clearly understand:
- Construction payment schedule
- Disbursement Schedule
- Pre-EMI liabilities, if any
- Ownership timeline
- Developer-buyer contract
- RERA registration
- Project approvals
The lender’s approval does not mean that all legal aspects of the project are acceptable. The buyer should independently verify the project’s Haryana RERA registration, title, approvals, and contract-related documents.
Home Loans and Gurugram Property Due Diligence
Financing and legal due diligence should be hand-in-hand. Before you buy, consider the following:
- Title and ownership history
- Deed of conveyance/sale
- Costs
- RERA registration
- plans approved
- Occupancy/completion status (if applicable)
- Maintenance charges
- Property taxes
- Developers documentation
- Permission of the authorities
- Land use status as appropriate
Haryana has also moved towards greater transparency in property transactions. In 2026, the state proposed to make the registration of Agreements to Sell mandatory, so as to increase legal certainty and reduce the risks of transactions carried out without registration.
This is a reminder of an important principle, that buyers should require proper documentation and not informal assurances.
Should You Choose a Longer or Shorter Tenure?
There is no universally correct tenure.
Longer tenure
Advantages:
- Lower EMI
- Greater monthly cash-flow flexibility
- Easier affordability
Disadvantages:
- Higher total interest
- Debt remains for longer
Shorter tenure
Advantages:
- Faster repayment
- Lower overall interest cost
- Faster increase in home equity
Disadvantages:
- Higher EMI
- Greater monthly financial commitment
For many borrowers, a practical strategy is to choose a tenure that makes EMIs comfortable and make additional principal payments when surplus funds are available, provided the terms of the loan and applicable regulations allow.
Common Home Loan Mistakes to Avoid
- Getting the Most Out of Your Loan: Bank eligibility is not the same as personal affordability
- Choosing solely by interest rate: A slightly lower rate may not be worth the higher fees or less favourable terms.
- Not accounting for the total cost of purchase: Add registration, stamp duty, interior decoration, maintenance deposits, broking fees if applicable and other transaction costs.
- Maintain an ample emergency reserve at all times. Putting all your savings to work
- Don’t ignore the fine print: Be aware of reset clauses, benchmark, spread, prepayment provisions and other charges.
- Believing Property Prices Will Always Rise: Property markets can experience times of slower growth, oversupply or localised corrections.
- Skipping Legal Verification: A lender’s diligence doesn’t substitute for the buyer’s independent legal review.
Government Support and Affordable Housing
Also, eligible buyers should verify whether they are eligible for government housing assistance.
The interest subsidy scheme under PMAY-U 2.0 for eligible urban households is still available subject to certain conditions. The updated guidance for 2026 supports eligible economically weaker, low-income, and middle-income households subject to scheme requirements.
You must meet the scheme’s income, property, loan, and other conditions to be eligible. Buyers should verify the current official guidelines before assuming that a subsidy will apply to their particular purchase.
For many premium Gurugram properties, such schemes may not be applicable because eligibility depends on prescribed property and income criteria.
Is 2026 a Good Time to Take a Home Loan in Gurugram?
There is no single answer that works for everyone. What is the right time depends on the buyer’s financial situation, choice of property and investment horizon. With the repo rate at 5.25%, there is a fairly stable policy backdrop at the moment, but borrowers should remember that interest rates can change in the future. For a real end user that had this:
- Regular income
- Enough Down Payment
- Emergency fund savings
- Good credit history
- A comfortable EMI capacity
- real estate
- A long-term investment horizon
2026 can be a reasonable environment to evaluate home ownership. However, buyers should avoid purchasing simply because they expect interest rates or property prices to move in a particular direction.
Buy the property because it fits your long-term needs and finances—not because of a short-term market prediction.
Conclusion
Getting your home loan approved is more than simply funding your dream house in Gurugram. It’s about structuring your finances so you can afford the property comfortably and sustainably.
The 2026 lending environment presents a relatively stable policy rate scenario for borrowers with the RBI repo rate at 5.25%. Homebuyers should however be prepared for the changes in interest rates over a long tenure of loan.
The best place to start is not with the property brochure but with your finances. Calculate your savings, down payment, monthly income, existing liabilities and comfortable EMI. Shop around and compare lenders and look at the total cost of the loan.
In the case of Gurugram itself, due diligence on property has to be backed by strict financing decisions. Before signing up for a long-term liability, check out the title, approvals, RERA status, developer credentials, construction quality and infrastructure.
If used responsibly, a home loan can be a powerful financial tool. The goal is not to borrow the maximum possible amount or chase the lowest advertised interest rate. The goal is a balance of homeownership, financial security, and wealth building over the long term.
Ready to take the next step? Enquire Now.
Related reading: